Inside The Akamai and AT&T Deal and Why Akamai May Have Paid Too Much

The media is spending a lot of time regurgitating the Akamai and AT&T press release but from what I’ve seen, none are digging under the surface to see what’s really going on. Some like the WSJ even said that as a result of the new deal, AT&T and Akamai will now “end competition” amongst each other, which is laughable. Anyone who follows the CDN space, which clearly the WSJ doesn’t, knows that AT&T was never competing with Akamai, or anyone else for that matter when it came to their failed CDN business. The simple fact that the WSJ and other sites don’t even mention what AT&T or Akamai’s CDN revenues are shows they really don’t get the market. Others have made comments like, “the deal eliminates AT&T as a rival” which is also not true. Based on numbers Akamai has given out in the past, and the AT&T numbers I know of, AT&T is doing around 1% of Akamai’s CDN revenue. How is that a “rival”?

Reuters said that the AT&T deal, “follows Akamai’s similar agreement with France Telecom’s Orange last month”, which is not accurate. Akamai’s deal with AT&T is not a licensed CDN deal. It’s a straight reseller deal. Akamai’s announcement with Orange is for a licensed CDN deal where Orange licenses Akamai’s software to run on the Orange network. AT&T is not deploying any software from Akamai on their network, so the two deals are not at all alike, something that Akamai confirmed with me on a call with them this morning.

I’ve also seen a couple of telco bloggers say this deal isn’t good for EdgeCast, which isn’t the case at all. While none would go on the record for this piece regarding numbers, I talk often with executives at all three companies and one critical fact that’s missing from every story so far is that Akamai committed $100M to AT&T to secure a resale deal. That might seem smart on the surface but if you know the space well, you know that it’s just not a scalable strategy. It doesn’t surprise me that this deal would be applauded by shareholders but most don’t have any insight into AT&T’s CDN business and to date, I have never seen a single report that even says what AT&T’s CDN revenue is, aside from the number they used from my blog, which was $10M last year and less than $20M this year.

While EdgeCast is nowhere near the size of Akamai, I expect they will do about $75M in 2012, EdgeCast is years ahead of Akamai in the carrier space and have vastly more white-label resellers overall. By my last count I think it is more than 60, including telcos like DT and large web hosts such as Softlayer. EdgeCast earned millions from AT&T in licensing fees (my sources estimate the amount at $25-50 million) and they will continue to do so for some time. Meanwhile, Akamai is spending $100M partly to try to stop their momentum and also get access to AT&T’s network. Sure, that’s a much cheaper way to buy into the telco space than acquiring EdgeCast would be, but it’s a staggering price to pay to pick up a reseller. Committing eight and nine figure sums to resellers is simply not a repeatable model, especially since EdgeCast already has deep relationships with many of the largest resellers.

Yet many are suggesting that what Akamai is doing with AT&T is a blueprint for what they will do with other carriers when it’s not. Akamai only has a few hundred million in cash, so they definitely can’t afford to buy their way into all these resellers and operators, especially for a service like CDN, which has low margins. And most telcos and carriers have been actively building out their own CDNs, or using licensed and managed CDN products, which is a business Akamai has only just entered, years behind others. Most telcos, carriers and MSO don’t want to simply resell services, but rather have more control over them since they own the network.

Some have suggested to me that once Akamai’s LCDN product is out of beta that AT&T could buy out their EdgeCast contract and replace EdgeCast’s LCDN solution with Akamai’s, but that’s not likely. I’ve also heard some say that Akamai bought Verivue to try to get an LCDN product to market faster so they could try and get it into AT&T and push out EdgeCast, but that’s not happening. Remember that Juniper spent $100M buying Ankeena just to please AT&T and then AT&T didn’t end up going with them. Akamai’s deal with AT&T is not around LCDN and won’t be any time soon.

So, what will be left when the dust settles? There will be AT&T’s wholesale CDN platform, with hundreds of servers running EdgeCast software and delivering paid customer traffic for massive brands that AT&T services today on their CDN. None of these big brand customers that I speak with are interested in having their production traffic moved off a stable platform and onto a new one. So AT&T is at risk of churning the CDN business they do have if they try to force their customers onto a third-party platform they don’t operate.

As for the growing federated traffic being sent to AT&T by EdgeCast and Pacnet, clearly that cannot migrate to Akamai’s platform under the newly announced deal since this is not a licensed CDN (LCDN) agreement with AT&T and right now, Akamai has no LCDN product outside of what’s currently in beta. So AT&T can either keep their wholesale platform up, or go back on their commitments to the global carrier community (via OCX, etc.) to promote CDN Federation.

There will also be the interesting drama of AT&T trying to figure out how to resell Akamai services to AT&T enterprise customers, a large number of which are already Akamai customers. One final fact is that the CDN that AT&T launched (at the cost of well over $100M) before they signed with EdgeCast is still running. Now they are going to add an Akamai CDN to this mix, which means running three separate CDNs until they shut down their own and migrate over to Akamai. That’s a lot to ask for a company that has never shown any expertise with their CDN business or strategy.

As I wrote last year, the way AT&T could get serious about CDN would be to acquire a CDN operator, but they don’t seem interested in doing this. One could suggest they don’t want to acquire low-margin CDN products, but they also had the right of first refusal to acquire Cotendo, who had high-margin value add services, and they passed on that before Akamai acquired them, even though AT&T told me that Cotendo’s services were very important to the company with, “40-60% of all new customers in their sales pipeline” needing such a solution. So AT&T is not really serious about this business if all they want to do is resell it. Some would suggest the opposite by saying that AT&T can now rely on Akamai to help them do it right, but if AT&T could not sell a simple CDN service that they owned, how are they going to resell CDN services they no longer control? It’s asking a lot from AT&T.

I’ve also seem some that suggest the CDN business with AT&T isn’t really important as it’s all the “value added services” that AT&T will resell that will bring Akamai revenue. While that’s a nice idea, it’s not the majority of what AT&T will be reselling. Akamai confirmed with me today that AT&T will sell CDN including their media services, software downloads, small object delivery and DSA. But that’s a far cry from the complex, customized, high-margin services Akamai offers that require a lot of professional services. That’s not something AT&T will be able to sell at scale.

The real benefit to Akamai is not what AT&T might be able to resell, it’s the fact that Akamai now gets to place their servers inside AT&T at the regional level. Akamai confirmed for me that before this deal, they didn’t have any of their servers directly within AT&T’s network and had to peer with them instead. So from a QoS and capacity standpoint, this deal is good news for Akamai and AT&T customers but Akamai isn’t saying how much additional capacity it gives them or the difference in QoS. But at the cost of $100M, Akamai paid a lot of money to get inside AT&T’s network, with the hope that AT&T can also bring them a lot of reseller revenue.

Another thing to watch from this deal is Akamai’s costs. While Akamai talks a lot about how many servers they have and how they are at the “edge”, which is a vague term, the deal with AT&T shows that Akamai never actually had servers within AT&T’s network. Now they are spending a lot of money to get that access and this might open them up to other telcos who now see that Akamai is willing to write big checks to get inside telco networks. It will be interesting to see if other telcos now ask Akamai for a large sum to have access inside their network as well. If that happens, and Akamai needs to have more than just peering access, then this could get expensive for Akamai in the long-term. While I don’t know if this will happen, it’s reasonable to think it could, considering Akamai’s deal with AT&T is public for all the other telcos to see.

AT&T has simply never been able to get their CDN act together and now they are going to try another approach, by reselling Akamai, and change their strategy once again. Time will tell, but in two years we could be looking back on this recent agreement between Akamai and AT&T and realize that Akamai picked up the tab for the most expensive deployment inside a carrier in history.
Sponsored by

AT&T Finally Gives Up On Their In-House CDN: Will Resell Akamai’s CDN Services

[See my follow up post here: Inside The Akamai and AT&T Deal and Why Akamai May Have Paid Too Much] In August I reported that AT&T was planning to shut down their in-house CDN and re-sell CDN services from Akamai or Limelight Networks and that Akamai would probably win the deal since they were willing to guarantee AT&T more business than Limelight would. This morning, AT&T and Akamai made the deal official with an announcement saying the two companies will work to jointly sell CDN services in North America to start, expanding to outside the U.S. in twelve months. For AT&T, this signals what is almost a thirteen year effort to try to get their CDN business off the ground, dating back to 2000 when they launched their ICDS platform (Intelligent Content Distribution Service).

While today’s announcement is good for Akamai, there’s not a lot of revenue attached to it. AT&T will do less than $20M in total CDN revenue this year and it will take them and Akamai a long time to sell a joint solution in the market, let alone one that can handle content delivery outside the U.S. I don’t expect today’s announcement to affect AT&T’s wholesale CDN services and federation model, so I would expect AT&T would still manage that portion of their CDN business with EdgeCast’s platform. Customers who are currently buying this solution from AT&T purchase it from a wholesale division of the company, not from an enterprise sales team, so the new re-seller deal with Akamai should not impact AT&T’s wholesale CDN business, which continues to grow.

While enterprise customers could also go direct to Akamai, most of AT&T’s large enterprise contracts are for multiple products, including things like co-location, transit and managed services, which are services Akamai does not offer. So AT&T isn’t trying to get CDN only business with a re-seller deal like this, but rather want to use CDN to keep or get them more of the non-CDN business they already have. It will be interesting to watch how both companies manage channel conflicts, since a very large percentage of enterprise customers are already taking services from Akamai, but one would assume that’s something they have already worked out with this deal.

At the time of this post, Akamai’s shares are up $3.20, which makes no sense since the revenue associated with this deal is so small to start. I’ve seen more than a dozen articles taking about the deal and about Akamai’s shares being up, but none of them discuss what the value of this contract could be worth to Akamai, or what AT&T’s current CDN revenue is.

Thursday Webinar: “Making Transparent Caching a Reality”

Thursday at 2pm ET I’ll be moderating another StreamingMedia.com webinar, on the topic of, “Making Transparent Caching a Reality“. Telcos, mobile and cable operators face increasing costs of bandwidth delivery needed to meet the demand for online video and a quality viewing experience, while being forced to invest heavily into maintaining their network infrastructure. As a result, a growing number of operators are turning to transparent caching solutions to reduce the adverse impact of OTT video traffic in their environment.

Several vendors have developed various technologies to address the video traffic challenges. But, as analysts, have observed, some solutions are more adept than others. Join us for an informative and entertaining webinar in which our speakers will discuss the video caching issues that matter, as well as looking at some of the solutions available in the marketplace. Along the way you’ll also learn about what makes Qwilt’s own Universal Video Delivery technology tick.

During this 60-minute webinar you will learn:

  • why transparent caching is rapidly being adopted amongst operators worldwide
  • different caching network architectures and their impact on operator networks
  • which technology considerations matter the most

Register here and bring your questions for the presenters for the live Q&A portion of the event.

Apple Having Major Supply Issues: New iMac’s and iPad Mini’s Won’t Ship In Time For Holidays

Four days ago I bought one of the new 21″ Apple iMac’s in the store and when I tried to purchase another today, they were all sold out. None of the Apple stores around me have them in stock and each store said they did not know exactly when they would get them back in, with one employee saying it would be “at least a few weeks”. My local Apple store said they didn’t get very many in to begin with and while they didn’t give me an exact number they did say they received “less than 50”.

Trying to buy one via Apple.com and the wait is 10 business days before it ships. When I called Apple, they said it takes 7 business days to be delivered after it ships. So if it takes a total of 17 business days to get delivered, the delivery date would be December 27th. And that’s if they ship on time, which the person I spoke to at Apple saying that was a “best case scenario”. Trying to get one of the new iPad mini’s is no better with the shipping time being 14 business days. So that puts the iPad mini delivery date at January 2nd. And if you want the new 27″ iMac, realistically that’s not going to get delivered until the end of January.

I know Apple has acknowledged that they are having some supply chain problems, but one had to imagine this is really going to impact their sales during the holidays. No one wants to get someone a gift that won’t show up until weeks after the holiday.

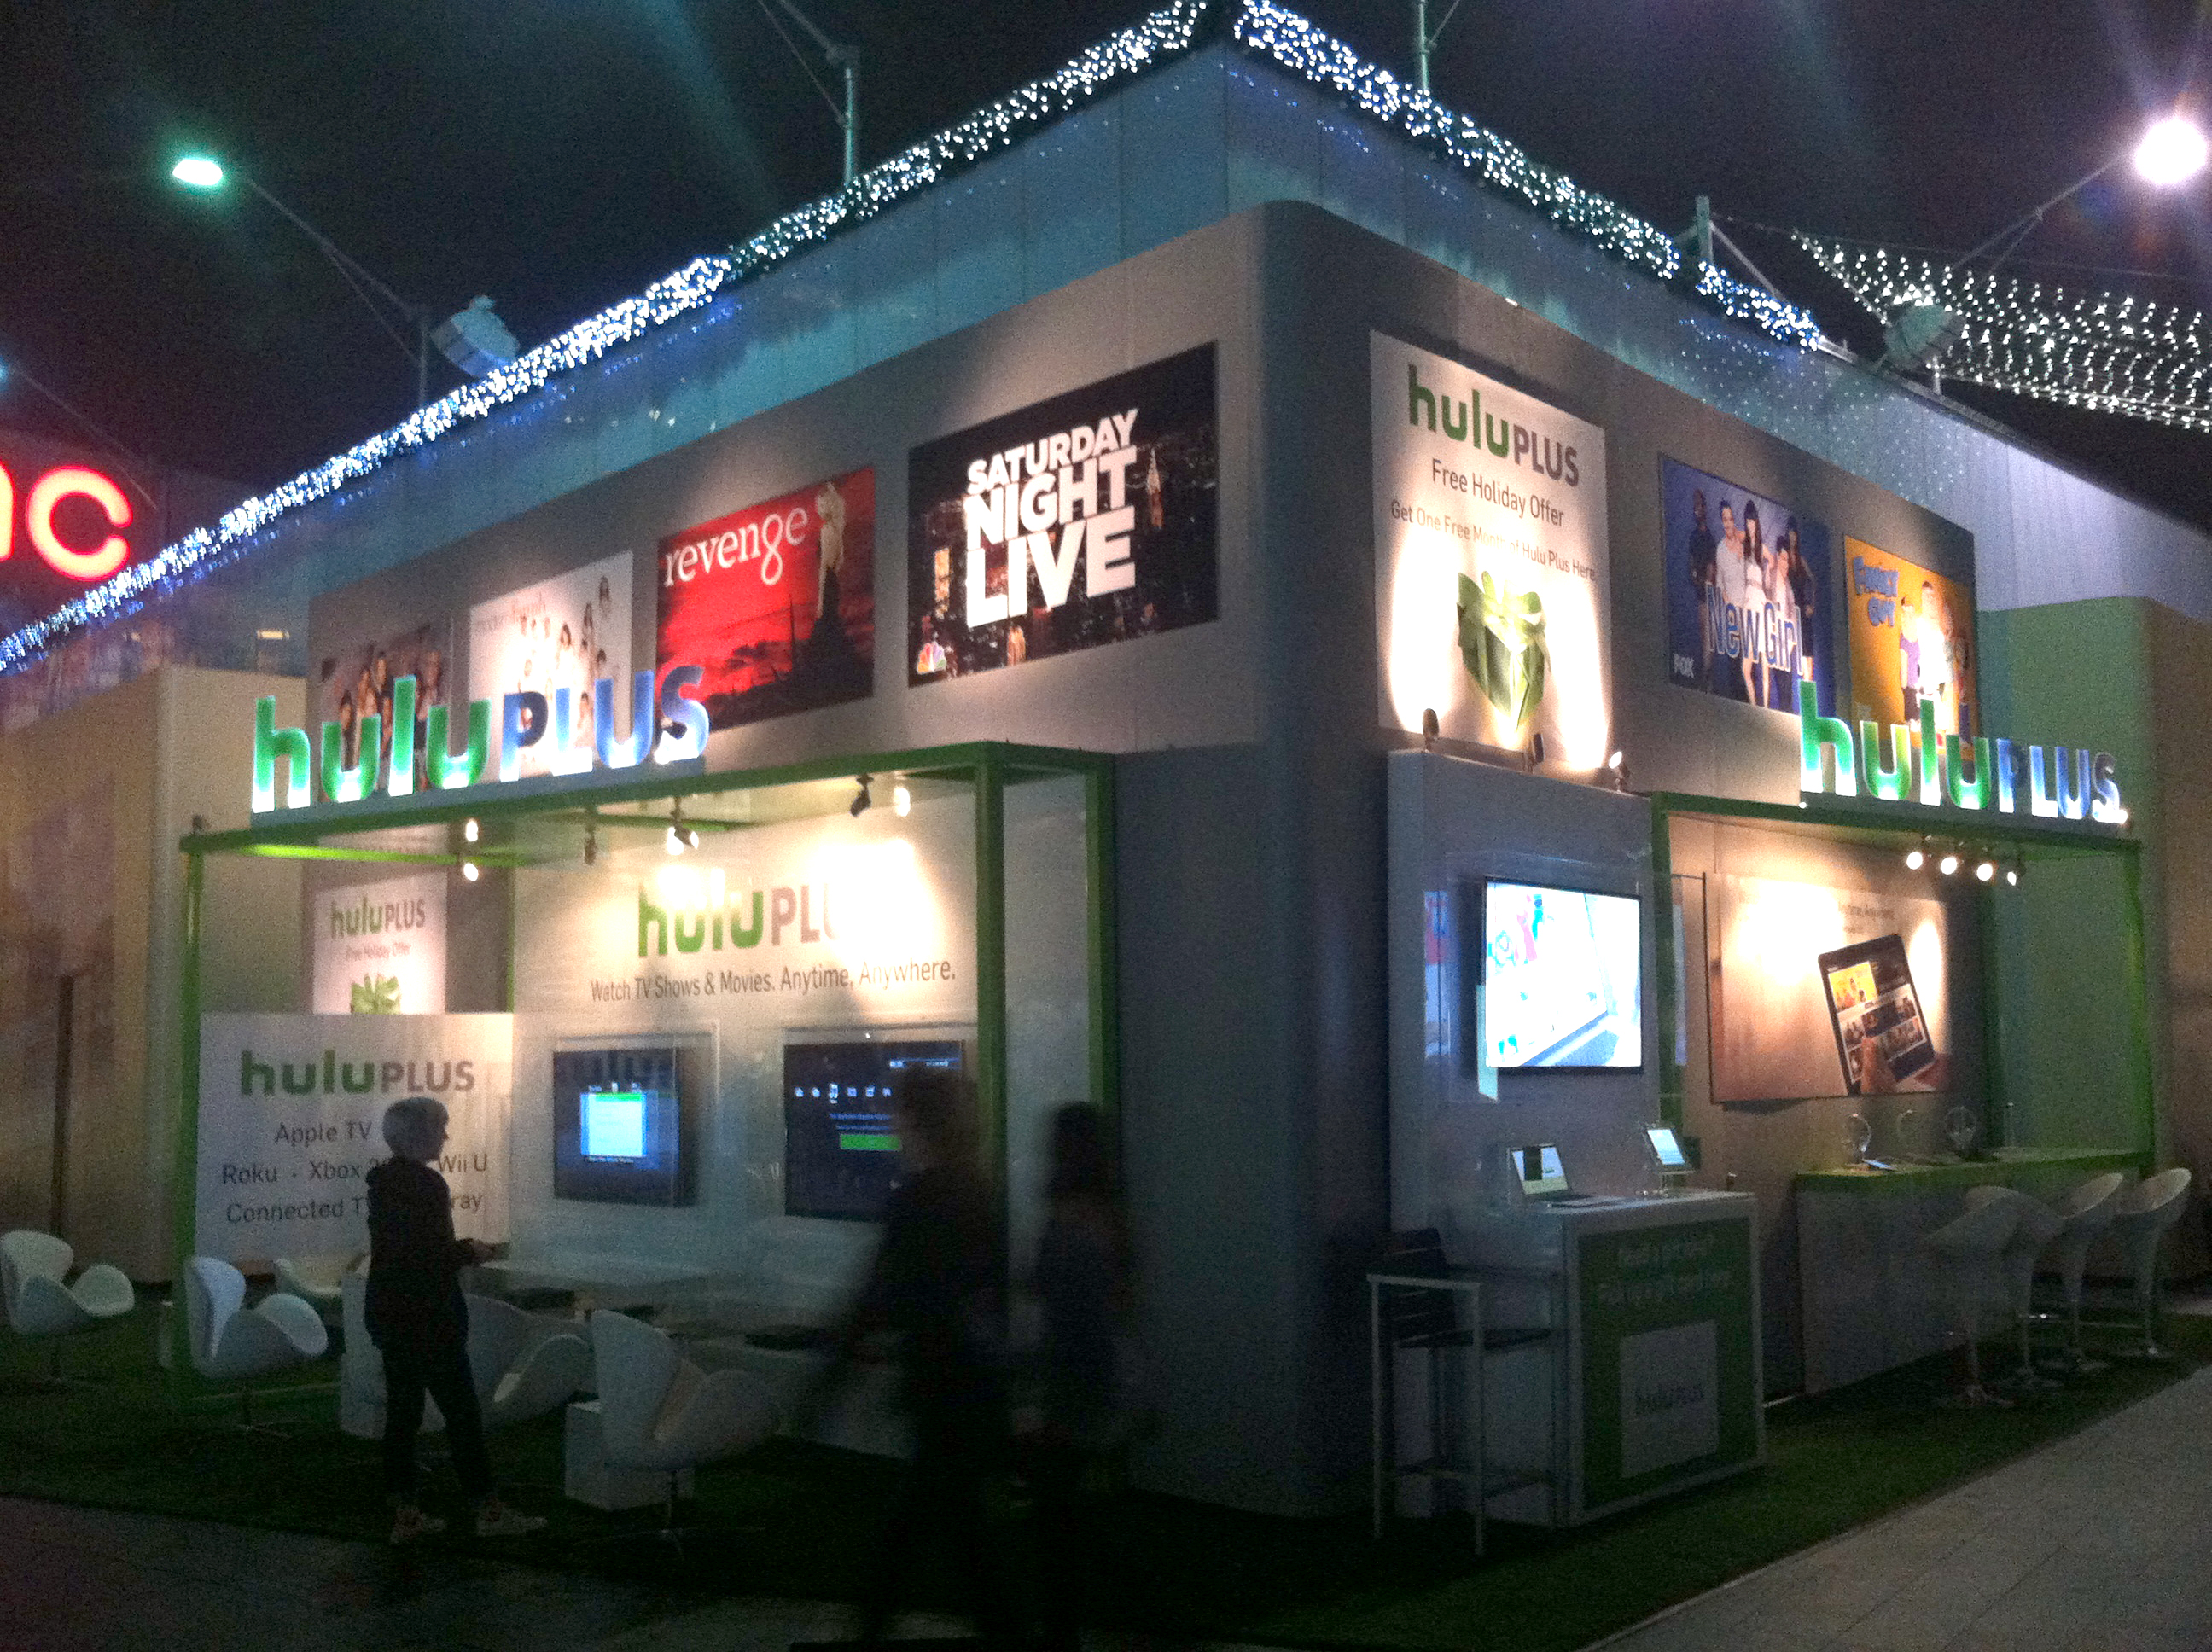
Hulu Opens A Pop-Up Store In Century City, Lets People Test Out Hulu Plus

I don’t know if Hulu has more of these, but in Century City California, Hulu has taken over part of the retail space of a restaurant that’s been boarded up and has opened a pop-up store. You can get hands-on with Hulu’s streaming service and check out how it works on multiple devices. Not sure if this going to be a permanent mini-store or was setup just for the holidays, but it’s a great idea for letting consumers test out Hulu’s service. Click on the image to see a higher-res copy of the photo.

Call For Speakers Now Open For The 2013 Content Delivery Summit

Now in its fifth year, my special Content Delivery Summit is a one-day conference designed to bring together telecom carriers, service providers, content owners, and industry vendors for a detailed look at CDN platforms for the delivery of video and content acceleration. The Content Delivery Summit (#cdnsummit) is the most focused show in the industry on the topic of CDN and the one all the others try to copy.

The 2013 show will take place on Monday, May 20th at the Hilton hotel in NYC and will include case studies on real-world deployments, demos of new technology platforms and discussions on business model considerations for web acceleration and media delivery. The call for speakers is now open and here’s some of the topic that will be covered at the show:

  • Over-The-Top Video Delivery
  • Dynamic Site Acceleration
  • Transparent Caching
  • Application Acceleration
  • CDN Economics & Business Models
  • CDN Pricing & Volume Data
  • Front-End Optimization
  • Managed/Licensed CDN
  • Analytics & Cloud Intelligence
  • Telco CDN Deployments
  • Mobile Content Acceleration
  • The Business of CDN Federation

If you are interested in speaking at the event, please fill out the speaking request form. I’m looking for moderators who want to lead sessions, stand-alone presenters who can share deployment data, case studies from customers who are implementing various CDN technologies and I will also be selecting a few vendors to demo new products and services being launched around the show.

We get a great mix of speakers and attendees to the show from MSOs, ISPs, Telcos, Carriers and major content owners such as:

  • BT, Telus, Korea Telecom, Vodafone, Netflix, Cablevision, Bell, Google, Comcast, Telefonica, Time Warner Cable, Verizon, Pacnet, AT&T, Global Crossing, Yahoo!, Xbox, Telecom Argentina, Deutsche Telekom, Cox and Orange as well as all of the leading vendors and suppliers in the market including the newest startups.

To help me in creating the program for the Content Delivery Summit, I do dozens of calls with CDN customers and vendors to hear what they think should be covered in the agenda and I reach out to past attendees asking them what additional topics they want to see discussed. If you’d like to be involved in the show, have a customer that is interested in doing a case study, or want to give me feedback on anything pertaining to the CDN industry, please reach out to me. Unlike last year where I didn’t start working on the agenda until January, I will be placing speaking much earlier this year, so DO NOT wait until the submission deadline to submit. I am also looking for some good end-users for potential keynote opportunities.

If you are interested in sponsoring the CDN Summit, please contact Joel Unickow.

Free Giveaway: Win A New Slingbox 350 – The True TV Everywhere Device

If you are looking to access your full linear TV lineup wherever you go from your computer or mobile device, then the Slingbox is the only way to go. I’ve still got one brand new Slingbox 350 left over the Streaming Media West show last month and will give it away to one lucky reader of my blog.

To enter the drawing, just leave one comment on this post with your full name and submit the comment using a valid email address. I’ll pick one lucky winner at random next month. You must have a U.S. postal address as I will not ship it overseas outside the United States. Good luck!